Tax relief should come with a workable plan to sustain the services residents depend on.
Florida’s property tax system needs reform. Homeowners facing rising housing costs deserve meaningful relief, and residents have every right to demand efficient, accountable government.
But reform should come with a workable plan. Amendment 3, on the November 3, 2026 ballot, would reduce local property tax revenue while leaving communities to address a fundamental question: How will they maintain essential services with less money?
For Pinellas County residents, that question deserves as much attention as the potential tax savings.
A restaurant analogy explains the problem
Imagine a restaurant whose weekly income falls from $10,000 to $7,000. The owner is told that the remaining money must pay for food, employee wages, rent, and utilities.
Those are necessary expenses. But naming them does not reduce their cost or replace the missing $3,000. Unless the restaurant finds replacement income or sufficient savings, it may need fewer employees, shorter hours, or a smaller menu.
The numbers in this example are hypothetical. The budget problem facing local governments is real.
Police officers, firefighters, emergency medical personnel, and other public employees still need to be paid. Equipment, fuel, insurance, buildings, and maintenance still cost money. Restricting how revenue may be spent does not guarantee enough revenue to cover those expenses.
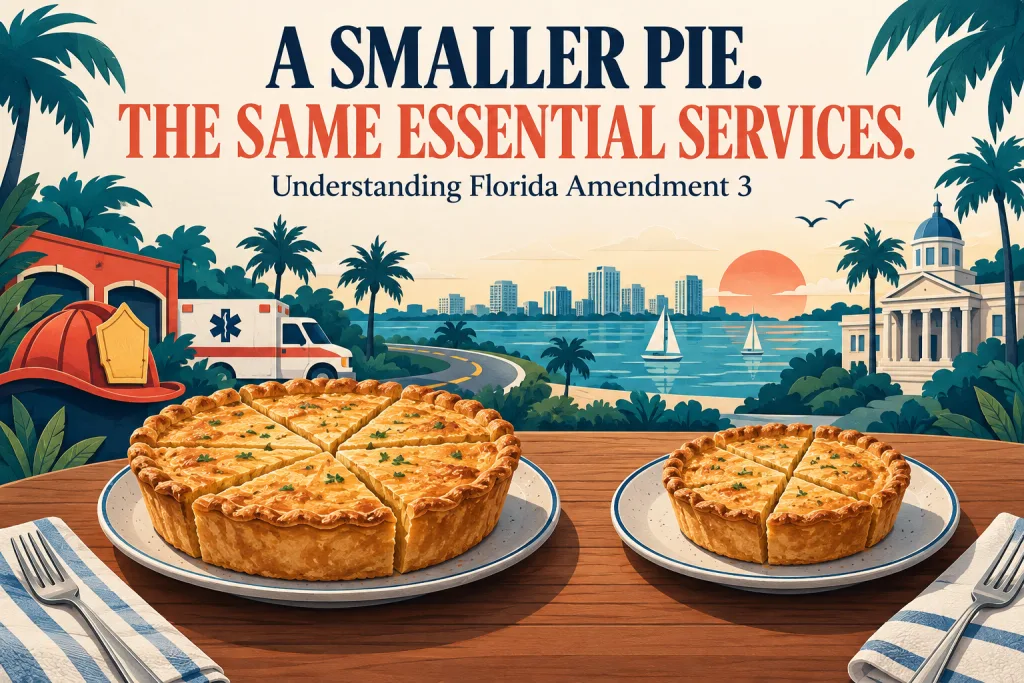
Labeling the slices does not make a smaller pie feed the same number of people.
What Amendment 3 would change
Amendment 3 would increase the homestead exemption for non-school property taxes to $150,000 in 2027 and $250,000 in 2028, with inflation adjustments afterward. It would also lower the annual cap on assessment increases for non-homestead properties from 10% to 5%.
A homestead exemption reduces the taxable value of a qualifying home. A $250,000 exemption is not a $250,000 reduction in the homeowner’s tax bill. Actual savings would depend on the property’s taxable value and applicable tax rates.
The expanded exemption would not apply to school district taxes. The proposal also includes different eligibility rules for people establishing Florida residency after December 31, 2026. Read the amendment summary from the Pinellas Supervisor of Elections.
The amendment identifies spending categories for county and municipal property tax revenue:
- Public safety, including law enforcement, fire protection, and emergency medical services
- Education and schools
- Infrastructure
- Natural resources
- Bond debt payments
- Employee retirement benefits
- Government operations and administration
The ballot language also allows other expenditures to be approved by county officers or local governing bodies unless prohibited by general law. It would therefore be inaccurate to say the amendment automatically bans funding for parks or libraries. Source: Pinellas Supervisor of Elections.
An allowed expense is not a funding guarantee
Identifying public safety as a permitted use of property taxes does not guarantee enough money to maintain existing police, fire, or emergency medical services.
Public safety would share the available revenue with other major obligations, including infrastructure, debt payments, retirement benefits, and government operations. Those costs do not automatically fall when property tax revenue declines.
Local officials would still have to balance their budgets. If demonstrated efficiencies cannot cover the gap, they would need replacement revenue, spending reductions, or some combination of both.
What this could mean in Pinellas
Clearwater provides a concrete local example. The city reports preliminary estimates of approximately $12 million less in property tax revenue in the first year and an additional $8 million reduction the following year if Amendment 3 passes.
Those estimates concern Clearwater alone—not the entire county—and describe projected revenue reductions, not an adopted list of service cuts. See Clearwater’s explanation of property taxes and city services.
The effects across Pinellas would vary. County government, individual cities, and special districts have different tax bases, responsibilities, and funding arrangements. There is no single budget decision that would determine the outcome for every resident.
Depending on how local governments respond, reduced revenue could mean fewer staff, reduced service hours, delayed maintenance or projects, or higher fees or tax rates to help close the gap.
These are possible responses—not confirmed outcomes. Claims that a particular fire station, library, or program will close require specific evidence.
But uncertainty about which services might be affected does not remove the need for a credible funding plan. Residents deserve to understand the tradeoffs before a permanent constitutional change takes effect.
Even legislative leaders who advanced it now oppose it
Opposition to Amendment 3 includes Republican leaders who helped put it before voters.
Senate President Ben Albritton now says he will vote no, citing the potential loss of resources for rural counties and the consequences for law enforcement, emergency response, and infrastructure. Former Senate President Kathleen Passidomo, who voted to place the amendment on the ballot, has also announced her opposition. Source: WLRN, October 21, 2026.
Passidomo explained that her legislative vote reflected her belief that voters should have the opportunity to decide. She argues that residents dissatisfied with local spending should hold their elected officials accountable at the ballot box. Source: Florida Politics, October 5, 2026.
Their positions reinforce a central point: supporting property tax reform does not require supporting this particular amendment.
Reform should answer both sides of the equation
Affordability matters. So does careful scrutiny of government spending. Residents should expect officials to identify waste, justify expenses, and demonstrate that public money is being used effectively.
They should also expect evidence that proposed savings can cover recurring revenue losses without undermining essential services. An assertion that government can “tighten its belt” is not a substitute for identifying which expenses can realistically be reduced and what those reductions would mean.
Before making a permanent constitutional change, voters deserve clear answers:
- What would qualifying homeowners actually save?
- How much revenue would each affected local government lose?
- Which efficiencies could realistically close the gap?
- Would fees or other taxes increase?
- What would happen to staffing, maintenance, and service availability if replacement funding falls short?
Pinellas residents should be able to evaluate the household savings alongside the community costs.
We agree that property tax reform is needed. We also believe it should be designed around a sustainable plan for the services people rely on every day.
Amendment 3 does not adequately resolve that challenge. Pinellas deserves a better approach.